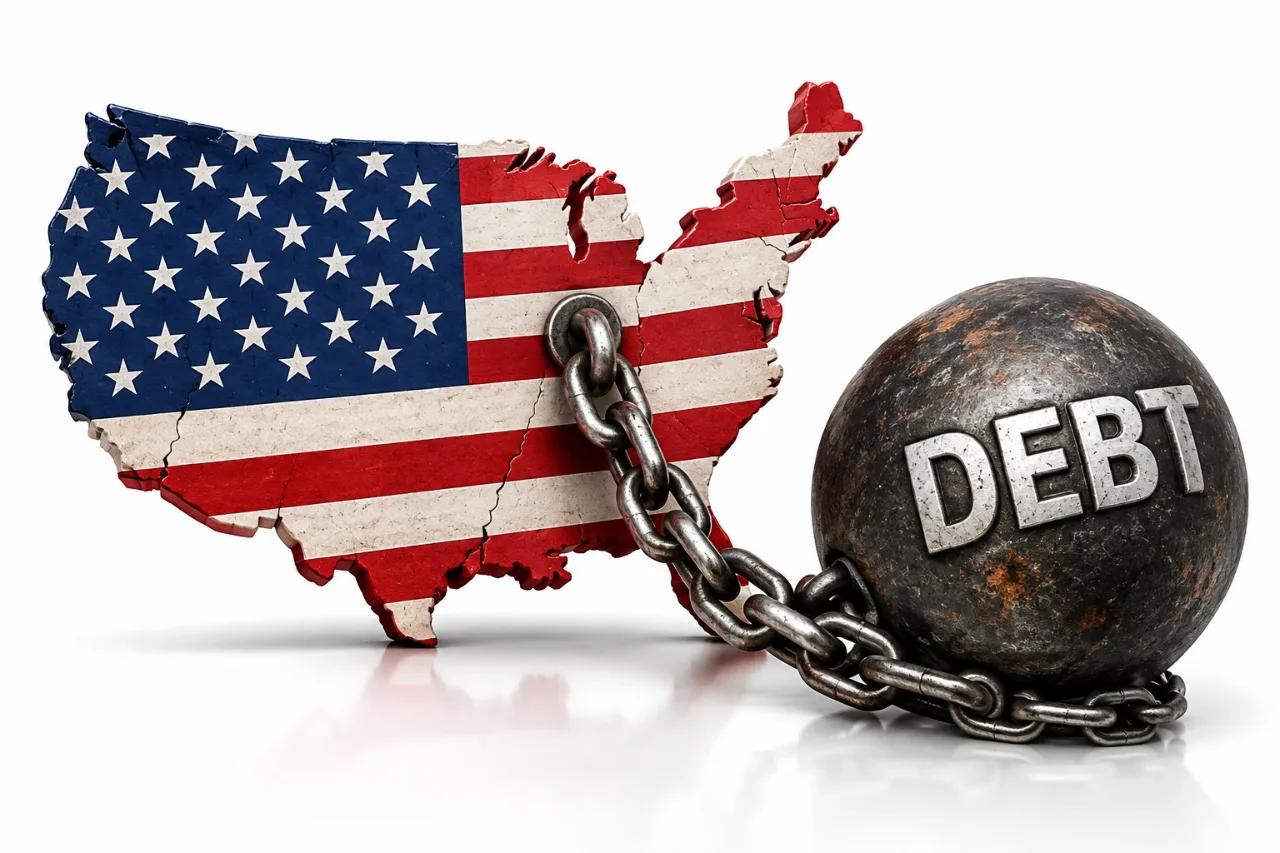
America’s fiscal position is beginning to resemble a train gathering speed on a dangerous mountain track. The economy remains resilient, but the federal government is running a deficit of roughly 6 per cent of GDP, while borrowing costs are placing increasing pressure on the budget.
The United States is not facing an imminent debt crisis. But the conditions that precede one are becoming harder to dismiss.
Debt crises rarely arrive with a single warning. They often begin after years in which high borrowing appears manageable because interest rates remain low. Then the cost of financing rises, investors become less tolerant and governments discover that the room for manoeuvre they assumed they had is disappearing.
That is increasingly relevant to Washington.
The United States benefited for years from exceptionally cheap borrowing. Much of that debt, however, was not locked in for decades at low rates. As older debt is refinanced at higher costs, interest payments are consuming a growing share of federal resources.
Within a remarkably short period, interest on the national debt has moved from a secondary concern to one of the largest items in the federal budget. It is on course to become the government's largest single expense.
That changes the political equation.
When interest costs rise, Washington has only a limited number of options. It can increase taxes, reduce spending or borrow still more. So far, borrowing has remained the preferred answer.
That strategy can continue for as long as investors believe the United States will eventually restore fiscal discipline. But markets do not offer unlimited patience.
The danger is not simply the size of America’s debt. The United States retains enormous economic strengths, deep financial markets and the privilege of issuing the world’s principal reserve currency. Those advantages give Washington considerably more fiscal flexibility than most other governments.
They also create a temptation to assume that flexibility is permanent.
The current political environment reinforces that temptation.
The Trump administration has emphasised economic growth as a way of improving the fiscal outlook. Treasury Secretary Scott Bessent has argued that stronger growth can help address the country’s financial pressures.
Growth certainly matters. A larger economy produces more tax revenue and can make a given debt burden easier to carry.
But growth cannot be treated as a substitute for fiscal adjustment indefinitely.
There is also uncertainty over how much additional revenue the artificial-intelligence boom will generate for the government. The technology could significantly increase productivity and economic output, but higher productivity does not automatically translate into enough additional tax revenue to close a structural fiscal gap.
Meanwhile, political incentives continue to push in the opposite direction.
President Donald Trump’s proposal to provide Americans with a $5,000 “dividend” if Republicans retain control of Congress would represent another potential fiscal commitment at a time when Washington is already struggling to contain its deficit.
The underlying problem is not unique to Trump. Both major US political parties have repeatedly found it easier to promise benefits than to impose the taxes or spending reductions required to pay for them.
That is how fiscal problems accumulate.
The critical variable now is interest rates.
If borrowing costs remain contained, Washington could continue managing a high debt burden for years. But a sustained rise in Treasury yields could quickly make the arithmetic more difficult. A prolonged war involving Iran, worsening political dysfunction or a loss of investor confidence could push long-term rates substantially higher.
Higher rates would increase interest payments. Higher interest payments would enlarge the deficit. A larger deficit would require more borrowing. More borrowing could put further pressure on yields.
That feedback loop is what makes debt crises dangerous.
The initial deterioration does not have to be dramatic. What matters is whether markets begin to believe that political leaders are unwilling or unable to change course.
Once that confidence weakens, governments can find themselves facing choices they had hoped to avoid: higher inflation, financial repression, sharp spending cuts, tax increases or, in extreme circumstances, default.
The United States remains far from that point.
But the consequences of even a serious debt scare would extend well beyond government finances. High borrowing costs could restrict Washington’s ability to respond aggressively to the next recession, financial crisis, war or major national emergency.
A government carrying a heavy debt burden has less freedom when the unexpected happens.
That is perhaps the most underappreciated risk.
America’s fiscal position leaves little room for error. A major war, natural disaster, cyberattack or financial shock could require enormous public spending precisely when the government has the least flexibility to provide it.
The United States also has an advantage that many other indebted advanced economies lack: the dollar’s position at the centre of the global financial system.
That privilege should not be mistaken for immunity.
Reserve-currency status can delay the consequences of fiscal excess. It cannot repeal the arithmetic of compound interest.
The political problem is therefore more serious than the economic one.
America has the resources, institutions and productive capacity to stabilise its finances. What it has lacked is a durable political consensus willing to accept the costs.
That consensus may not emerge until the alternatives become considerably more painful.
The danger is that markets could force that reckoning at precisely the wrong moment.
A responsible fiscal strategy does not require Washington to eliminate its deficit overnight or abandon investment in growth. It requires policymakers to demonstrate that the trajectory can be changed before investors demand proof.
For now, the United States still has time.
But time is not the same thing as unlimited fiscal space.
The longer Washington treats rising debt as tomorrow’s problem, the greater the risk that tomorrow’s problem eventually arrives as today’s crisis.